Security hold on a particular payment
Ask about the bank's confirmation procedure and deadline for that operation. A temporary anti-fraud payment pause is different from inclusion in the fraud database.
Russia bank restriction guide
If your bank card stops working after a casino payout, ask the bank what it has restricted and why. The order of events does not prove that the casino transfer caused the block. The written notice determines which documents and appeal route are relevant.
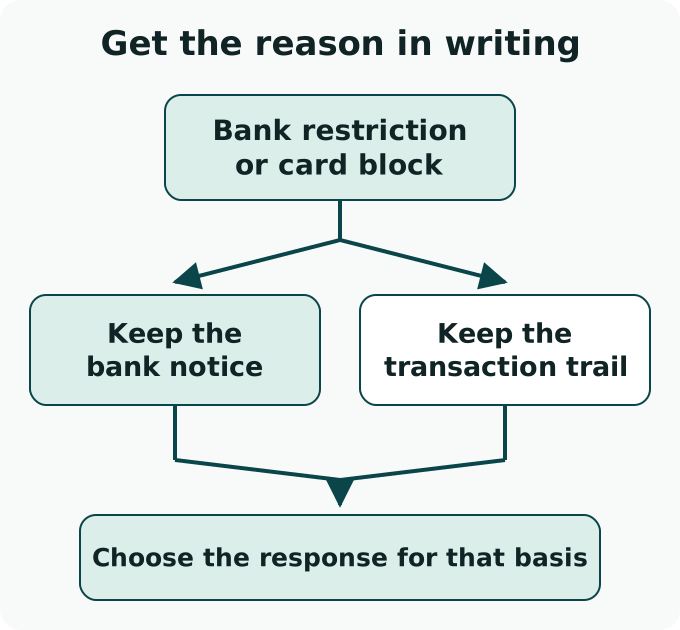
A request to explain incoming money, a formal refusal under 115-FZ and a restriction linked to the 161-FZ fraud database need different responses. Save the notice and the actual payout trail before choosing one.
Ask about the bank's confirmation procedure and deadline for that operation. A temporary anti-fraud payment pause is different from inclusion in the fraud database.
Obtain the exact provision, operation and requested evidence. Prepare a truthful explanation for the bank. The formal-refusal review route below applies when that is the decision actually made.
Ask which personal or payment details are included and follow the database-exclusion application procedure.
Prepare a 161-FZ exclusion applicationRequest the written ground, affected services, services still available, and the action or documents needed. A generic 'card blocked' label is too vague to select an appeal.
Have the bank distinguish the card, online banking, an individual transfer and the account itself. Ask whether you can submit an instruction or receive information at a branch, and which identification documents to bring. Do not assume that every service has been frozen because a card payment fails.
Request a specific document list with the transactions, counterparties and period it concerns. If you already supplied records, ask what is still missing and why those records did not answer the bank's question. Keep the response and its reference.
Keep the statement showing the date, amount, currency, sender description and reference. Preserve the wording even if the sender is a payment intermediary rather than the casino's brand.
Save the request, account identifier, sent amount and operator's payment reference. Explain any difference between the requested and received amounts with the genuine fee or conversion record.
Include the real wallet, exchange or payment-service records that connect the stages. A crypto transaction hash and a separate ruble sale can help explain a trail, but one does not prove the other without matching records.
Answer the actual questions and attach relevant genuine evidence. Income documents may be relevant when requested; they are not a universal substitute for explaining this particular incoming payment.
For formal refusals covered by Article 7(5.2) or 7(11), the bank provides the date and reasons within five working days. Record the operation or account-opening request concerned.
The bank's reconsideration period is seven working days from receipt of the documents. Keep proof of submission and its response. New material can support another application.
Use the MVK application route in the Bank of Russia Internet reception. Prior reconsideration by the bank is required. The commission reviews the application within 20 working days; it concerns the specified refusal.
Restrictions on a card or remote banking alone are outside MVK's refusal-review scope. So are card issue or reissue disputes, tariff disputes and anti-fraud payment pauses. Do not file an MVK application merely because the bank notice mentions 115-FZ; identify whether it contains a formal operation or account-opening refusal.
If the bank has only restricted remote access, ask for the applicable complaint procedure and available branch instructions. If it identifies fraud-database inclusion, use the separate 161-FZ route. A favourable decision on one refusal does not resolve unrelated restrictions.
State the refusal dates, operation and reasons, the organisation's name and bank registration number or nonbank OGRN, and relevant dates of your relationship with it. Include the original refusal if available.
Provide your name, date of birth, citizenship or absence of citizenship, identity-document details, correspondence address and taxpayer number (INN) if available. Include applicable foreign residence-permission details and relevant public-official position details.
For a Russian passport, attach pages 2 and 3 and the pages containing residence-registration stamps. Supply applicable foreign residence-permission documents where required.
Attach the evidence you sent for reconsideration and the bank's message that it could not remove the grounds for refusal. Explain how the documents address those grounds.
If represented, include the representative's identity and authority documents. Original transaction papers, further evidence and an account statement for the preceding year can supplement the required packet. Check the current individual's form before submitting.
Give the bank or commission a dated sequence: the incoming payment, the restriction or refusal, the bank's request, your response and the decision. Number attachments so the reviewer can follow the money without guessing which screenshot belongs to which transaction.
If the response repeats a broad demand, ask which specific fact remains unexplained. If it identifies another legal ground, reassess that part separately. A card replacement or a different casino withdrawal destination does not remove a restriction on the existing bank relationship.
Keep the bank's actual sender description and ask the casino for its payout reference and the payment intermediary involved. Connect the records through amounts, dates and references rather than inventing a sender identity.
Submitting records enables review; it does not guarantee that the bank will remove the stated grounds. Keep the reasoned reply so you can choose the applicable next procedure.
Ask about your specific restrictions and take identification. The 161-FZ electronic-payment restriction has its own branch-access rules, while another account restriction or legal ground can change what is available.
Use this route when the bank confirms the relevant database inclusion.
Establish whether the payment was sent, returned or credited.
Connect genuine funding, wallet and conversion records.